A Military Move Should Not Put a Spouse’s Career on Pause
RETURN TO BLOG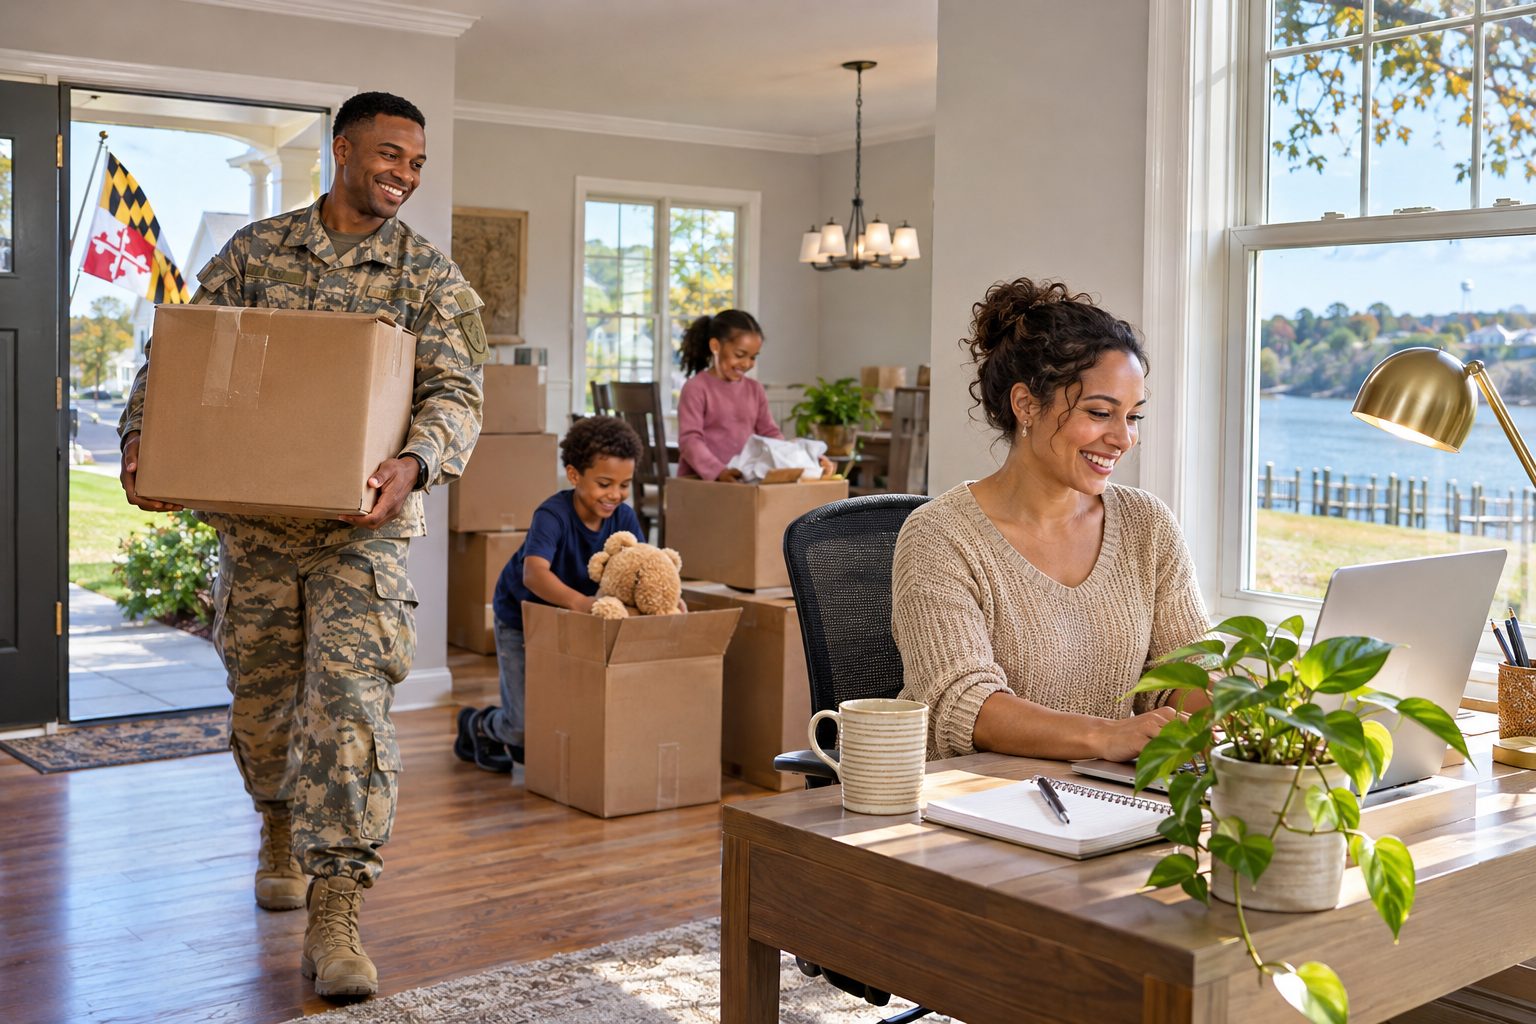
A PCS move is not only a housing deadline. It can affect two careers, childcare, licensing, remote-work space, commute, school timing, benefits and the household’s financial margin. A responsible real estate plan makes room for the whole household.
Southern Maryland serves families connected to Joint Base Andrews, Naval Air Station Patuxent River, Washington and other assignments. A home that looks close on a map may feel very different after Route 4 traffic, bridge schedules and two separate workdays enter the picture.
If you are planning a PCS move and trying to protect both careers, start with my Military Relocation Plan. You can tell me your report date, budget, housing priorities and what you need for remote work, even if your orders are not final yet. Then explore my Military Base Home Search to compare communities near your installation before deciding which location works for the whole household.
What caught my attention in the Zillow story
Zillow’s culture story profiles military spouses who found career continuity through distributed work. It is an employer-focused national story, not a Southern Maryland housing study. The local lesson I take from it is that the spouse’s work, licensing and space needs should be part of the housing plan from the first conversation.
Remote work is not location-free magic. Buyers should verify internet service, cellular backup, room layout and any employer security requirements at the exact address.
A spouse who expects to change jobs may affect mortgage documentation and timing. The lender needs accurate information before an offer, not a cheerful surprise during underwriting.
Sometimes renting first is the smart PCS choice. Sometimes a carefully timed purchase works. The goal is not to win a race against the moving truck. The goal is to land the household safely.
Source and category check: Zillow published Careers that move with you: How military spouses find stability and growth at Zillow on November 13, 2025. It appears in Zillow's Zillow Culture category. Zillow did not sponsor, review or endorse this article. The analysis here is my own.
Dawn’s rule: Separate verified facts from assumptions. Then send each unresolved question to the professional or agency that controls the answer. A good contract strategy does not blur those roles.
Start with the property-specific question
A PCS move is not only a housing deadline. It can affect two careers, childcare, licensing, remote-work space, commute, school timing, benefits and the household’s financial margin. A responsible real estate plan makes room for the whole household. That distinction matters because buyers and sellers often hear a shorthand answer and treat it as final. A listing description, seller memory, online map or contractor opinion can be useful, but none automatically controls title, financing, insurance, permitting or legal rights.
Southern Maryland serves families connected to Joint Base Andrews, Naval Air Station Patuxent River, Washington and other assignments. A home that looks close on a map may feel very different after Route 4 traffic, bridge schedules and two separate workdays enter the picture. Dawn begins by writing down the client’s intended use, the evidence already available and the deadline for a reliable answer. That prevents research from becoming an open-ended project and keeps the parties focused on what could change price, terms or willingness to proceed.
Records buyers and sellers should collect
Documents usually reveal more than reassurance. Collect the following records early, preserve the original file names and note the source and date. If a record is missing, label it missing. Do not replace it with an assumption.
- Official orders and reporting timeline when available
- Current employment, remote-work and licensing requirements for both adults
- Lender preapproval reflecting expected income and employment changes
- Lease, sale and temporary-housing dates
- Internet-provider availability at candidate addresses
- Commute plans, childcare needs and home-office requirements
These records should be read together. A permit without a final inspection, a survey without the referenced easement, or an estimate without a defined scope can create false confidence. Dawn builds one shared checklist and tracks who requested each item, when it arrived and which professional still needs to review it.
Local warning signs that deserve a closer look
- An employment change is hidden from the lender
- Internet service is assumed from a coverage map alone
- The household commits before comparing both commutes
- A VA benefit is treated as automatic loan approval
- Temporary lodging and storage costs are omitted
- The seller needs possession after closing but the buyer must arrive immediately
A warning sign is not proof of a defect, denial or legal violation. It is a reason to slow down and ask a narrower question. The strongest due diligence says, “Here is what we observed, here is the controlling document or agency, and here is the answer we need before this date.”
In Calvert County, rural land, waterfront, private systems and community restrictions often overlap. One professional cannot answer every layer. A contractor may estimate a repair but cannot guarantee lender acceptance. A county employee may explain permits but not interpret a private contract. A Realtor can organize the transaction but does not replace legal, engineering, insurance or tax advice.
Verified rules and practical limits
- VA loan eligibility and lender approval are separate questions
- Employment and income changes can affect underwriting
- Remote-work suitability depends on the exact address and employer rules
- A PCS does not guarantee a particular contract concession
- Renting may preserve flexibility for an unfamiliar assignment
- The signed contract controls possession and settlement timing
These are starting points, not a substitute for a property-specific decision. Programs, forms and underwriting requirements can change. Dawn verifies the current rule with the controlling professional and keeps the written answer with the transaction file.
A practical buyer checklist
- Step 1: Tell the lender about known job and income changes before writing. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 2: Test internet and cellular options at the exact address. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 3: Map both commutes during realistic hours. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 4: Keep reserves for travel, temporary housing and repairs. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 5: Coordinate inspection and settlement with orders without assuming extensions. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 6: Choose a property that supports the household’s work and family plan. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
Buyers should prioritize questions that can end the purchase, change the monthly cost or make the planned use impossible. Cosmetic preferences can wait. Title, financing, insurance, safety, legal use and expensive physical conditions cannot. The contract should preserve enough time to receive real answers rather than merely submit requests.
A practical seller checklist
- Seller action 1: Ask for realistic settlement and possession dates. Early documentation protects credibility and gives the seller more choices.
- Seller action 2: Evaluate financing strength without demanding private military details. Early documentation protects credibility and gives the seller more choices.
- Seller action 3: Prepare property records so a remote buyer can review efficiently. Early documentation protects credibility and gives the seller more choices.
- Seller action 4: Use accurate video and virtual-tour support. Early documentation protects credibility and gives the seller more choices.
- Seller action 5: Put any post-settlement occupancy terms in writing. Early documentation protects credibility and gives the seller more choices.
- Seller action 6: Keep the property accessible for inspectors and appraisers. Early documentation protects credibility and gives the seller more choices.
Sellers gain leverage by solving uncertainty before a buyer turns it into a worst-case estimate. That does not mean repairing everything or agreeing with every concern. It means describing the property accurately, producing records quickly and understanding the likely cost and timing of any real issue before negotiating.
Related planning: Review Renting or Buying? Start With the Life Plan, Not the Headline; Review Home Features That Deserve More Than a Trend Label; Review AI Listing Photos Should Help Buyers, Not Fool Them. These guides are designed to go live together, so the research, financing and negotiation questions connect.
How this issue can affect the transaction
| Area | Possible effect |
|---|---|
| Use | office space and connectivity can be essential, not decorative. |
| Financing | employment transitions require lender review. |
| Insurance | vacancy or delayed occupancy should be disclosed accurately. |
| Appraisal | the VA or lender follows program requirements. |
| Title | remote signing and powers of attorney need early coordination. |
| Marketability | reliable records help relocation buyers decide from a distance. |
| Seller net | timing concessions may matter as much as price. |
| Deadlines | orders and contract dates must be coordinated but remain separate. |
Not every possible effect will apply. The purpose of the table is to prevent tunnel vision. A buyer may solve a physical concern and still have a lender problem. A seller may agree to a credit and still lack insurable title or carrier approval. Each lane must reach its own answer.
Who should answer each part?
| Professional | What that professional should answer |
|---|---|
| Dawn Riley and the real estate team | Organize documents, identify contract deadlines, coordinate questions, compare offer terms and keep advice from each licensed professional in the correct lane. |
| Title company or real estate attorney | Review recorded instruments, ownership, liens, deed language, settlement charges and legal questions. Only an attorney should give legal advice. |
| Lender and appraiser | Decide loan eligibility, underwriting treatment, valuation requirements and documentation. A real estate agent cannot approve financing or direct an appraisal result. |
| Inspector, engineer or specialty contractor | Evaluate physical conditions within the professional scope and explain repair options. A general home inspection does not replace engineering or environmental review. |
| Insurance producer | Confirm whether coverage is available, what it costs, which exclusions apply and what underwriting records are required. |
Dawn’s job is to make sure the correct question reaches the correct professional before the relevant decision date. She can explain the Maryland contract process, organize evidence and negotiate terms. She will not present a guess as a legal, underwriting, engineering, appraisal, insurance or tax conclusion.
A realistic Southern Maryland transaction example
A family moving toward Patuxent River likes a Huntingtown home, but one spouse will keep a remote position while the other has a new duty station. We verify internet at the address, test the two commutes, tell the lender about the employment structure and compare purchase timing with temporary housing. The home decision includes both careers, not just the shortest route to one gate.
This example is illustrative, not a prediction. Property facts, contract language and professional decisions vary. What remains consistent is the method: identify the uncertainty, obtain the controlling evidence, calculate the effect and decide before leverage disappears.
How Dawn organizes the contract and negotiation strategy
I ask what must be true on reporting day, on the spouse’s first workday and thirty days after closing. Those answers shape settlement, possession, inspection access and financing. I never promise that orders will make a seller or lender waive a requirement.
Dawn Riley brings more than 25 years of Maryland real estate experience, detailed contract knowledge and Master Certified Negotiator training to that process. Her career includes 1,338+ sales and more than $532,653,786 in volume, with average sold-to-list statistics over 101%. Those numbers do not guarantee a result. They support a disciplined approach to pricing, documentation and negotiation.
Common mistakes to avoid
The first mistake is treating a verbal answer as a permanent fact. The second is asking the wrong professional to guarantee an outcome outside that person’s authority. The third is waiting until settlement week, when moving plans, rate locks and emotions make clear decisions harder.
Another mistake is assuming a credit cures everything. Money can address a known cost, but it does not create a permit, change a title right, make a lender approve the loan or force an insurer to issue coverage. The remedy must match the actual problem.
The Bottom Line
A PCS move is not only a housing deadline. It can affect two careers, childcare, licensing, remote-work space, commute, school timing, benefits and the household’s financial margin. A responsible real estate plan makes room for the whole household. Collect the records, identify the controlling authority, calculate the transaction impact and protect the deadline. Buyers deserve enough evidence to make an informed decision. Sellers deserve a strategy that does not discount the property simply because information was disorganized.
Frequently Asked Questions
Not automatically. Compare assignment length, market conditions, cash, employment, commutes and the value of flexibility. Renting first can be a sound choice.
A job change may affect underwriting. Tell the lender before making the change or writing the offer and obtain current guidance in writing.
No. Eligibility is one part of a VA loan. The lender still reviews income, credit, debts, property and program requirements.
Check provider service at the exact address, ask for current account information when available and confirm speed, equipment and installation timing directly with the provider.
Sometimes, subject to lender, title, military and state requirements. Start the review early and use approved language.
The parties may negotiate a written amendment, but neither side should assume an extension. Temporary housing and contingency plans matter.
That is a property-specific risk decision. Military timing does not remove the need to understand condition, well, septic, insurance and repairs.
Only through a carefully written occupancy agreement approved for the transaction. The buyer’s lender and insurer may have requirements.
Use live video, detailed photographs, floor plans and local inspections, but recognize that remote tools do not replace professional due diligence.
She organizes the housing timeline around verified orders, financing, both careers, inspections and possession while referring military, legal and lending questions to the proper professionals.
About Dawn Riley
Dawn Riley is an Associate Broker, Realtor, Master Certified Negotiator (MCNE) and Pricing Strategy Advisor (PSA) with The Riley Team at Deep Roots Real Estate in Huntingtown, Maryland. She has more than 25 years of real estate experience and additional negotiation coursework from Yale, Northwestern, UVA, Columbia and UC Davis. Dawn combines strategic pricing, advanced marketing and detailed Maryland contract knowledge for buyers and sellers throughout Calvert County and Southern Maryland.
Career results as of 2026: 1,338+ homes sold, $532,653,786+ in sales volume and average sold-to-list price statistics over 101%, per Bright MLS career production records. Past performance does not guarantee a specific result.
Dawn Riley
Associate Broker, Realtor, MCNE, PSA
The Riley Team at Deep Roots Real Estate
2425 Solomons Island Rd., Suite C, Huntingtown, MD 20639
410-414-2438
dawn@dawnriley.net
Schedule a consultation