Why the Square Footage Numbers Do Not Always Match
RETURN TO BLOG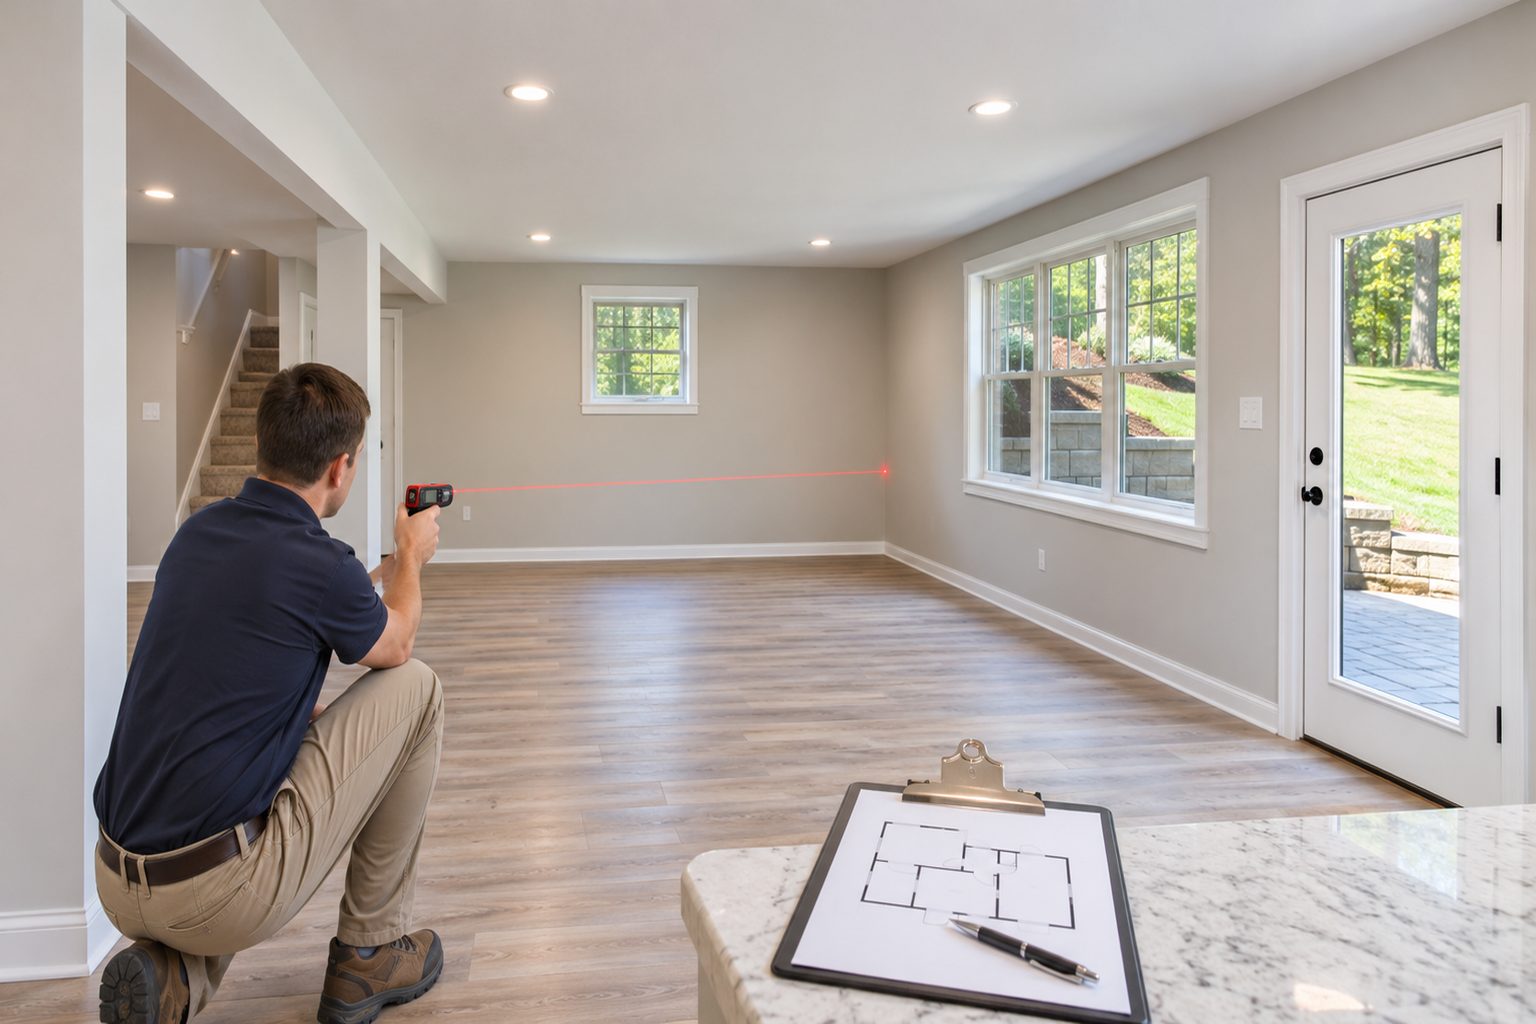
Tax records, listing data, floor plans and appraisals can show different square footage because they serve different purposes and may use different sources or measurement standards. The right response is to identify the source, method and space included.
Calvert County homes often have walkout lower levels, additions, converted porches and detached finished spaces. A buyer may love every inch and still need to know which inches are above grade, permitted, heated and included in the appraisal. That is less romantic than the sunset view, but considerably easier to finance.
Dawn’s rule: Separate verified facts from assumptions. Then send each unresolved question to the professional or agency that controls the answer. A good contract strategy does not blur those roles.
Start with the property-specific question
Tax records, listing data, floor plans and appraisals can show different square footage because they serve different purposes and may use different sources or measurement standards. The right response is to identify the source, method and space included. That distinction matters because buyers and sellers often hear a shorthand answer and treat it as final. A listing description, seller memory, online map or contractor opinion can be useful, but none automatically controls title, financing, insurance, permitting or legal rights.
Calvert County homes often have walkout lower levels, additions, converted porches and detached finished spaces. A buyer may love every inch and still need to know which inches are above grade, permitted, heated and included in the appraisal. That is less romantic than the sunset view, but considerably easier to finance. Dawn begins by writing down the client’s intended use, the evidence already available and the deadline for a reliable answer. That prevents research from becoming an open-ended project and keeps the parties focused on what could change price, terms or willingness to proceed.
Records buyers and sellers should collect
Documents usually reveal more than reassurance. Collect the following records early, preserve the original file names and note the source and date. If a record is missing, label it missing. Do not replace it with an assumption.
- SDAT property record and assessment details
- Permits, approved plans and final inspections
- Seller records for additions and conversions
- Marketing floor plan with measurement disclaimer
- Appraisal report and measurement sketch when available
- Septic approval and bedroom records where room count is relevant
These records should be read together. A permit without a final inspection, a survey without the referenced easement, or an estimate without a defined scope can create false confidence. Dawn builds one shared checklist and tracks who requested each item, when it arrived and which professional still needs to review it.
Local warning signs that deserve a closer look
- The listing total combines detached space with the main home
- Below-grade finished area is presented as above-grade
- A porch or garage conversion lacks supporting permits
- Ceiling height or access affects how appraisers classify an area
- The tax record has not been updated after permitted work
- Price-per-square-foot comparisons mix inconsistent definitions
A warning sign is not proof of a defect, denial or legal violation. It is a reason to slow down and ask a narrower question. The strongest due diligence says, “Here is what we observed, here is the controlling document or agency, and here is the answer we need before this date.”
In Calvert County, rural land, waterfront, private systems and community restrictions often overlap. One professional cannot answer every layer. A contractor may estimate a repair but cannot guarantee lender acceptance. A county employee may explain permits but not interpret a private contract. A Realtor can organize the transaction but does not replace legal, engineering, insurance or tax advice.
Verified rules and practical limits
- Fannie Mae requires ANSI Z765-2021 for applicable single-family appraisal assignments
- Above-grade and below-grade finished areas are reported separately under the guidance
- Tax assessment records do not serve the same purpose as an appraisal
- A marketing floor plan is not a survey or appraisal
- Permitted use, finished area and bedroom status are separate questions
- The appraiser must follow assignment and investor requirements
These are starting points, not a substitute for a property-specific decision. Programs, forms and underwriting requirements can change. Dawn verifies the current rule with the controlling professional and keeps the written answer with the transaction file.
A practical buyer checklist
- Step 1: Ask for the source behind the advertised number. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 2: Compare the floor plan with the property in person. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 3: Review permits for additions and conversions. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 4: Ask the lender how below-grade or detached space is treated. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 5: Measure furniture-critical areas independently. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 6: Value function and market reaction, not one ratio alone. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
Buyers should prioritize questions that can end the purchase, change the monthly cost or make the planned use impossible. Cosmetic preferences can wait. Title, financing, insurance, safety, legal use and expensive physical conditions cannot. The contract should preserve enough time to receive real answers rather than merely submit requests.
A practical seller checklist
- Seller action 1: Choose a defensible source before publishing square footage. Early documentation protects credibility and gives the seller more choices.
- Seller action 2: Separate above-grade, below-grade and detached areas clearly. Early documentation protects credibility and gives the seller more choices.
- Seller action 3: Gather permits and plans before photography. Early documentation protects credibility and gives the seller more choices.
- Seller action 4: Avoid unsupported bedroom or living-area claims. Early documentation protects credibility and gives the seller more choices.
- Seller action 5: Correct known discrepancies promptly. Early documentation protects credibility and gives the seller more choices.
- Seller action 6: Price from comparable properties with similar functional space. Early documentation protects credibility and gives the seller more choices.
Sellers gain leverage by solving uncertainty before a buyer turns it into a worst-case estimate. That does not mean repairing everything or agreeing with every concern. It means describing the property accurately, producing records quickly and understanding the likely cost and timing of any real issue before negotiating.
Related planning: Review When the Market Slows, Prepared Buyers Gain Negotiating Room; Review A 7% Mortgage Rate Does Not Erase Every Buyer Advantage; Review AI Can Clear the Clutter, but It Cannot Replace Your Realtor. These guides are designed to go live together, so the research, financing and negotiation questions connect.
How this issue can affect the transaction
| Area | Possible effect |
|---|---|
| Use | finished space may be comfortable even if classified differently. |
| Financing | appraisal treatment can affect value and underwriting. |
| Insurance | construction and use should be described accurately. |
| Appraisal | measurement and comparable selection follow assignment standards. |
| Title | square footage does not prove ownership or permitted use. |
| Marketability | clear breakdowns reduce buyer suspicion. |
| Seller net | an inflated claim can trigger renegotiation or appraisal trouble. |
| Deadlines | permit and appraisal questions need time before settlement. |
Not every possible effect will apply. The purpose of the table is to prevent tunnel vision. A buyer may solve a physical concern and still have a lender problem. A seller may agree to a credit and still lack insurable title or carrier approval. Each lane must reach its own answer.
Who should answer each part?
| Professional | What that professional should answer |
|---|---|
| Dawn Riley and the real estate team | Organize documents, identify contract deadlines, coordinate questions, compare offer terms and keep advice from each licensed professional in the correct lane. |
| Title company or real estate attorney | Review recorded instruments, ownership, liens, deed language, settlement charges and legal questions. Only an attorney should give legal advice. |
| Lender and appraiser | Decide loan eligibility, underwriting treatment, valuation requirements and documentation. A real estate agent cannot approve financing or direct an appraisal result. |
| Inspector, engineer or specialty contractor | Evaluate physical conditions within the professional scope and explain repair options. A general home inspection does not replace engineering or environmental review. |
| Insurance producer | Confirm whether coverage is available, what it costs, which exclusions apply and what underwriting records are required. |
Dawn’s job is to make sure the correct question reaches the correct professional before the relevant decision date. She can explain the Maryland contract process, organize evidence and negotiate terms. She will not present a guess as a legal, underwriting, engineering, appraisal, insurance or tax conclusion.
A realistic Southern Maryland transaction example
A Huntingtown rambler is advertised with a large total finished area that includes a walkout lower level. The tax record shows a smaller number, and the appraisal reports above-grade and below-grade areas separately. That does not mean the lower level disappeared. We compare the sketch, permits, ceiling height, finish and comparable sales so the buyer understands function and the lender understands valuation.
This example is illustrative, not a prediction. Property facts, contract language and professional decisions vary. What remains consistent is the method: identify the uncertainty, obtain the controlling evidence, calculate the effect and decide before leverage disappears.
How Dawn organizes the contract and negotiation strategy
I avoid arguing that one number must defeat all others. I label the source, explain the measurement purpose and compare the home with properties that offer similar usable space. If a discrepancy matters to price or financing, we address it before the appraisal deadline becomes a fire drill.
Dawn Riley brings more than 25 years of Maryland real estate experience, detailed contract knowledge and Master Certified Negotiator training to that process. Her career includes 1,338+ sales and more than $532,653,786 in volume, with average sold-to-list statistics over 101%. Those numbers do not guarantee a result. They support a disciplined approach to pricing, documentation and negotiation.
Common mistakes to avoid
The first mistake is treating a verbal answer as a permanent fact. The second is asking the wrong professional to guarantee an outcome outside that person’s authority. The third is waiting until settlement week, when moving plans, rate locks and emotions make clear decisions harder.
Another mistake is assuming a credit cures everything. Money can address a known cost, but it does not create a permit, change a title right, make a lender approve the loan or force an insurer to issue coverage. The remedy must match the actual problem.
The Bottom Line
Tax records, listing data, floor plans and appraisals can show different square footage because they serve different purposes and may use different sources or measurement standards. The right response is to identify the source, method and space included. Collect the records, identify the controlling authority, calculate the transaction impact and protect the deadline. Buyers deserve enough evidence to make an informed decision. Sellers deserve a strategy that does not discount the property simply because information was disorganized.
Frequently Asked Questions
The MLS may use seller, appraisal or floor-plan information, while the tax record serves assessment purposes and may lag improvements. Ask for the source.
It may be valuable finished space, but appraisal standards generally report below-grade finished area separately from above-grade area.
ANSI Z765 provides a consistent method for measuring and reporting square footage. Fannie Mae requires it for applicable appraisal assignments.
It should not be silently combined. Describe the main dwelling and detached space separately and verify permits and lender treatment.
No. Permitting is important, but the appraiser also follows measurement, quality, utility and market-evidence requirements.
No. Review permits, approved use, zoning, septic and other relevant records.
It can be one comparison, but condition, location, layout, land, systems and space classification matter. Inconsistent square footage makes the ratio especially risky.
Use a qualified provider for the intended purpose. The appraiser follows appraisal standards, while a marketing floor plan has a different role.
Review the measurement sketch and classification with the lender and appraiser process. The parties can consider contract rights, price and other evidence.
State the source of each figure, separate categories clearly and provide records. Accuracy builds more confidence than one oversized number.
About Dawn Riley
Dawn Riley is an Associate Broker, Realtor, Master Certified Negotiator (MCNE) and Pricing Strategy Advisor (PSA) with The Riley Team at Deep Roots Real Estate in Huntingtown, Maryland. She has more than 25 years of real estate experience and additional negotiation coursework from Yale, Northwestern, UVA, Columbia and UC Davis. Dawn combines strategic pricing, advanced marketing and detailed Maryland contract knowledge for buyers and sellers throughout Calvert County and Southern Maryland.
Career results as of 2026: 1,338+ homes sold, $532,653,786+ in sales volume and average sold-to-list price statistics over 101%, per Bright MLS career production records. Past performance does not guarantee a specific result.
Dawn Riley
Associate Broker, Realtor, MCNE, PSA
The Riley Team at Deep Roots Real Estate
2425 Solomons Island Rd., Suite C, Huntingtown, MD 20639
410-414-2438
dawn@dawnriley.net
Schedule a consultation