
Prequalification, Preapproval, and Conditional Mortgage Approval
RETURN TO BLOG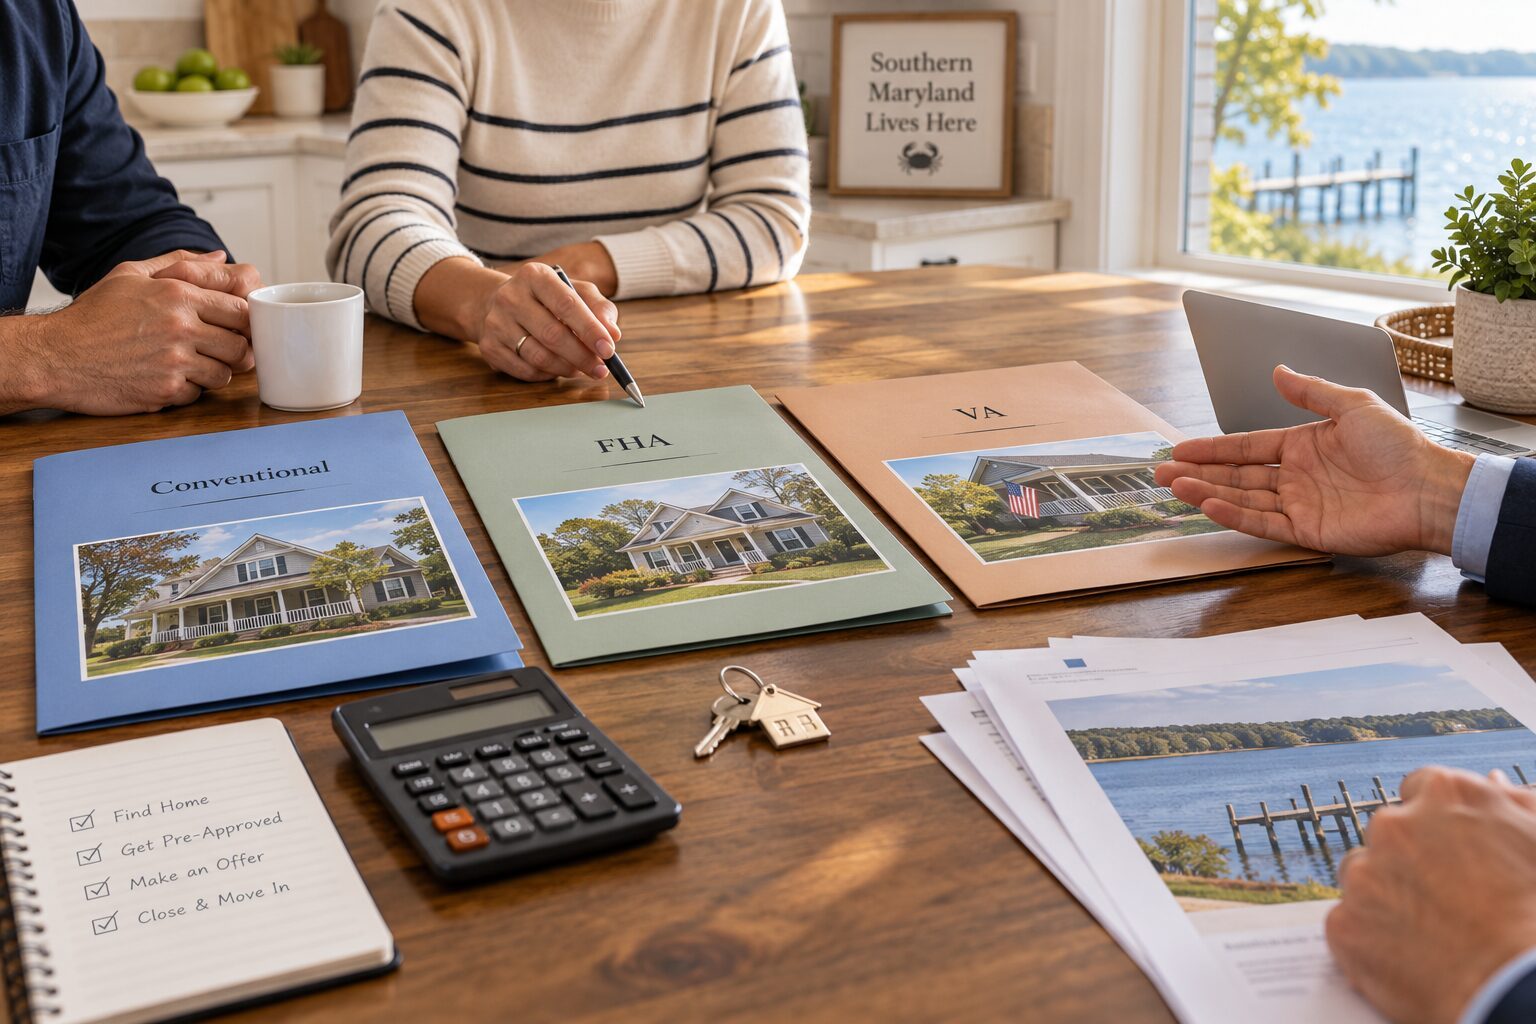
Lender letters often use similar words for very different levels of review. A prequalification may rely heavily on information supplied by the borrower. A preapproval may include credit, income and asset review. A conditional approval can be stronger, but it still contains conditions that must be satisfied before closing. The actual letter, lender process and outstanding conditions matter more than the label.
In Calvert County and Southern Maryland, sellers may be comparing conventional, VA, FHA and USDA offers while buyers are racing toward a competitive deadline. A local lender letter can help communication, but the lender name alone does not prove the file is fully reviewed. Property appraisal, title, insurance, employment, asset and sale-of-current-home conditions can remain.
Dawn’s rule: Separate verified facts from assumptions. Then send each unresolved question to the professional or agency that controls the answer. A good contract strategy does not blur those roles.
Start with the property-specific question
Lender letters often use similar words for very different levels of review. A prequalification may rely heavily on information supplied by the borrower. A preapproval may include credit, income and asset review. A conditional approval can be stronger, but it still contains conditions that must be satisfied before closing. The actual letter, lender process and outstanding conditions matter more than the label. That distinction matters because buyers and sellers often hear a shorthand answer and treat it as final. A listing description, seller memory, online map or contractor opinion can be useful, but none automatically controls title, financing, insurance, permitting or legal rights.
In Calvert County and Southern Maryland, sellers may be comparing conventional, VA, FHA and USDA offers while buyers are racing toward a competitive deadline. A local lender letter can help communication, but the lender name alone does not prove the file is fully reviewed. Property appraisal, title, insurance, employment, asset and sale-of-current-home conditions can remain. Dawn begins by writing down the client’s intended use, the evidence already available and the deadline for a reliable answer. That prevents research from becoming an open-ended project and keeps the parties focused on what could change price, terms or willingness to proceed.
Records buyers and sellers should collect
Documents usually reveal more than reassurance. Collect the following records early, preserve the original file names and note the source and date. If a record is missing, label it missing. Do not replace it with an assumption.
- Current lender letter naming the buyer, loan type and purchase range
- Loan application status and date of credit, income and asset review
- List of remaining borrower and property conditions
- Evidence for any required sale or settlement of another property
- Estimated cash-to-close and verified source of funds
- Lender contact information and permission for focused status questions
These records should be read together. A permit without a final inspection, a survey without the referenced easement, or an estimate without a defined scope can create false confidence. Dawn builds one shared checklist and tracks who requested each item, when it arrived and which professional still needs to review it.
Local warning signs that deserve a closer look
- One paragraph says prequalified while another says conditionally approved
- Approval depends on sale of a specific home not shown as a contract contingency
- The letter is old or written for a different property
- Assets or income are merely stated rather than documented
- The lender has not reviewed the contract, taxes, insurance or association costs
- The commitment date is treated as a guarantee of settlement
A warning sign is not proof of a defect, denial or legal violation. It is a reason to slow down and ask a narrower question. The strongest due diligence says, “Here is what we observed, here is the controlling document or agency, and here is the answer we need before this date.”
In Calvert County, rural land, waterfront, private systems and community restrictions often overlap. One professional cannot answer every layer. A contractor may estimate a repair but cannot guarantee lender acceptance. A county employee may explain permits but not interpret a private contract. A Realtor can organize the transaction but does not replace legal, engineering, insurance or tax advice.
A practical buyer checklist
- Step 1: Ask the lender to explain every approval term in plain language. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 2: Provide requested income, asset and identification records promptly. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 3: Disclose property-sale dependencies before writing the offer. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 4: Avoid new debt, job changes or unexplained transfers. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 5: Confirm the lender has the ratified contract and property data. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 6: Keep the agent updated when a condition changes. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
Buyers should prioritize questions that can end the purchase, change the monthly cost or make the planned use impossible. Cosmetic preferences can wait. Title, financing, insurance, safety, legal use and expensive physical conditions cannot. The contract should preserve enough time to receive real answers rather than merely submit requests.
A practical seller checklist
- Seller action 1: Read the full letter instead of relying on the heading. Early documentation protects credibility and gives the seller more choices.
- Seller action 2: Ask objective questions about completed review and remaining conditions. Early documentation protects credibility and gives the seller more choices.
- Seller action 3: Compare financing deadline, appraisal risk and property-sale dependency. Early documentation protects credibility and gives the seller more choices.
- Seller action 4: Evaluate proof of funds and estimated cash to close. Early documentation protects credibility and gives the seller more choices.
- Seller action 5: Protect confidential borrower information during verification. Early documentation protects credibility and gives the seller more choices.
- Seller action 6: Choose the best risk-adjusted offer, not simply the strongest adjective. Early documentation protects credibility and gives the seller more choices.
Sellers gain leverage by solving uncertainty before a buyer turns it into a worst-case estimate. That does not mean repairing everything or agreeing with every concern. It means describing the property accurately, producing records quickly and understanding the likely cost and timing of any real issue before negotiating.
Related planning: Review Maryland Escalation Clauses and Competing-Offer Proof; Review Backup Offers and Kickout Clauses in Maryland; Review Gift Funds and Large Deposits Before Mortgage Closing. These guides are designed to go live together, so the research, financing and negotiation questions connect.
How this issue can affect the transaction
| Area | Possible effect |
|---|---|
| Use | occupancy plans can be affected by a delayed or failed loan. |
| Financing | unresolved conditions determine whether final approval can issue. |
| Insurance | premium and coverage can change qualification. |
| Appraisal | property value and condition remain separate lender conditions. |
| Marketability | a failed contract can add days on market. |
| Seller net | extensions and carrying costs reduce the practical result. |
| Deadlines | commitment and settlement dates need different tracking. |
Not every possible effect will apply. The purpose of the table is to prevent tunnel vision. A buyer may solve a physical concern and still have a lender problem. A seller may agree to a credit and still lack insurable title or carrier approval. Each lane must reach its own answer.
Who should answer each part?
| Professional | What that professional should answer |
|---|---|
| Dawn Riley and the real estate team | Organize documents, identify contract deadlines, coordinate questions, compare offer terms and keep advice from each licensed professional in the correct lane. |
| Title company or real estate attorney | Review recorded instruments, ownership, liens, deed language, settlement charges and legal questions. Only an attorney should give legal advice. |
| Lender and appraiser | Decide loan eligibility, underwriting treatment, valuation requirements and documentation. A real estate agent cannot approve financing or direct an appraisal result. |
| Inspector, engineer or specialty contractor | Evaluate physical conditions within the professional scope and explain repair options. A general home inspection does not replace engineering or environmental review. |
| Insurance producer | Confirm whether coverage is available, what it costs, which exclusions apply and what underwriting records are required. |
Dawn’s job is to make sure the correct question reaches the correct professional before the relevant decision date. She can explain the Maryland contract process, organize evidence and negotiate terms. She will not present a guess as a legal, underwriting, engineering, appraisal, insurance or tax conclusion.
A realistic Southern Maryland transaction example
A Lusby seller receives a letter that calls the buyers prequalified in one section and conditionally approved in another. Dawn asks the lender, with permission, what income, assets and credit have been reviewed and whether approval depends on selling another house. The seller then compares that dependency with the contract language before choosing the offer.
This example is illustrative, not a prediction. Property facts, contract language and professional decisions vary. What remains consistent is the method: identify the uncertainty, obtain the controlling evidence, calculate the effect and decide before leverage disappears.
How Dawn organizes the contract and negotiation strategy
Dawn does not challenge a buyer personally or ask for private underwriting details. She converts confusing wording into performance questions: what has been verified, what remains, whether another property must sell, when appraisal will be ordered and whether the lender can meet the written dates. The seller gets a clearer risk picture without pretending any letter guarantees closing.
Dawn Riley brings more than 25 years of Maryland real estate experience, detailed contract knowledge and Master Certified Negotiator training to that process. Her career includes 1,338+ sales and more than $532,653,786 in volume, with average sold-to-list statistics over 101%. Those numbers do not guarantee a result. They support a disciplined approach to pricing, documentation and negotiation.
Common mistakes to avoid
The first mistake is treating a verbal answer as a permanent fact. The second is asking the wrong professional to guarantee an outcome outside that person’s authority. The third is waiting until settlement week, when moving plans, rate locks and emotions make clear decisions harder.
Another mistake is assuming a credit cures everything. Money can address a known cost, but it does not create a permit, change a title right, make a lender approve the loan or force an insurer to issue coverage. The remedy must match the actual problem.
The Bottom Line
Lender letters often use similar words for very different levels of review. A prequalification may rely heavily on information supplied by the borrower. A preapproval may include credit, income and asset review. A conditional approval can be stronger, but it still contains conditions that must be satisfied before closing. The actual letter, lender process and outstanding conditions matter more than the label. Collect the records, identify the controlling authority, calculate the transaction impact and protect the deadline. Buyers deserve enough evidence to make an informed decision. Sellers deserve a strategy that does not discount the property simply because information was disorganized.
Frequently Asked Questions
No. Lenders may use the terms differently, but a prequalification often involves a lighter initial review while a preapproval generally reflects review of credit and financial information. Ask the issuing lender what was actually verified.
It means the loan has received an approval subject to stated conditions. Those conditions may involve updated income, assets, employment, appraisal, title, insurance or sale of another property. It is not final clearance to close.
No. Borrower circumstances, property findings, title, appraisal and documentation can change. A letter is evidence of progress, not a promise that every condition will be satisfied.
If approval depends on sale or settlement of another property, that dependency should be understood immediately. The purchase contract must also be reviewed to determine whether the buyer has a related contingency.
With appropriate permission, the agent can ask focused questions about review level, loan type, property assumptions and timeline. The lender should not disclose unnecessary confidential borrower information.
No. Local availability can improve communication and knowledge of regional property issues, but underwriting quality, documentation, staffing and performance matter more than location alone.
The buyer submits the ratified contract, completes the application process, responds to underwriting requests and the lender evaluates the property through appraisal, title and insurance requirements.
Yes. New debt, missed payments, employment changes or asset movements can affect qualification. Buyers should consult the lender before opening credit or moving substantial funds.
Compare verified review, loan type, down payment, property-sale conditions, financing deadline, lender responsiveness and cash-to-close evidence. Do not rank offers by a single label.
She reads the letter line by line, identifies inconsistent language, asks authorized performance questions and connects each remaining condition to the contract calendar.
About Dawn Riley
Dawn Riley is an Associate Broker, Realtor, Master Certified Negotiator (MCNE) and Pricing Strategy Advisor (PSA) with The Riley Team at Deep Roots Real Estate in Huntingtown, Maryland. She has more than 25 years of real estate experience and additional negotiation coursework from Yale, Northwestern, UVA, Columbia and UC Davis. Dawn combines strategic pricing, advanced marketing and detailed Maryland contract knowledge for buyers and sellers throughout Calvert County and Southern Maryland.
Career results as of 2026: 1,338+ homes sold, $532,653,786+ in sales volume and average sold-to-list price statistics over 101%, per Bright MLS career production records. Past performance does not guarantee a specific result.
Dawn Riley
Associate Broker, Realtor, MCNE, PSA
The Riley Team at Deep Roots Real Estate
2425 Solomons Island Rd., Suite C, Huntingtown, MD 20639
410-414-2438
dawn@dawnriley.net
Schedule a consultation