
Flood Maps, Elevation Certificates, and Home Insurance
RETURN TO BLOG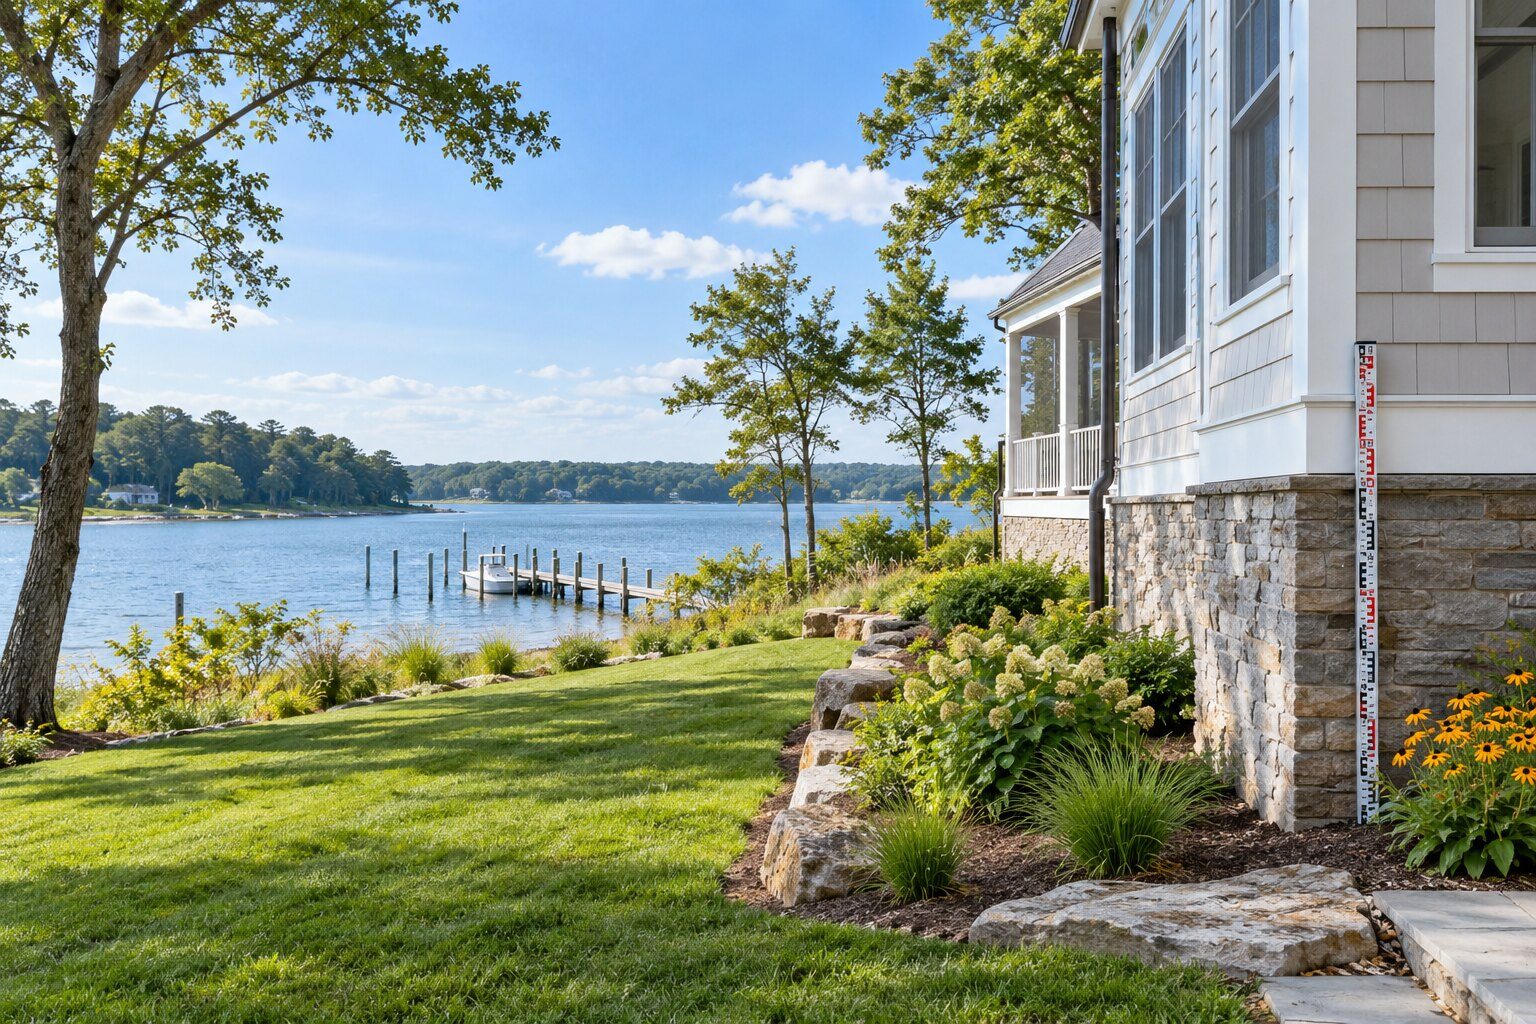
A flood-zone label is a starting point, not a complete risk or insurance answer. Buyers should review the effective map, current and future risk information, building elevation, prior claims, mitigation, lender requirements and an actual insurance quote before deciding that a waterfront or low-lying home is affordable.
Calvert County provides a Flood Hazard Map and adopted mitigation planning resources, while FEMA maintains the official Map Service Center. Shoreline, tidal, stormwater and drainage conditions can differ within the same community. An elevation certificate may help document building characteristics, but only the insurer can quote coverage and only the lender can state loan requirements.
Dawn’s rule: Separate verified facts from assumptions. Then send each unresolved question to the professional or agency that controls the answer. A good contract strategy does not blur those roles.
Start with the property-specific question
A flood-zone label is a starting point, not a complete risk or insurance answer. Buyers should review the effective map, current and future risk information, building elevation, prior claims, mitigation, lender requirements and an actual insurance quote before deciding that a waterfront or low-lying home is affordable. That distinction matters because buyers and sellers often hear a shorthand answer and treat it as final. A listing description, seller memory, online map or contractor opinion can be useful, but none automatically controls title, financing, insurance, permitting or legal rights.
Calvert County provides a Flood Hazard Map and adopted mitigation planning resources, while FEMA maintains the official Map Service Center. Shoreline, tidal, stormwater and drainage conditions can differ within the same community. An elevation certificate may help document building characteristics, but only the insurer can quote coverage and only the lender can state loan requirements. Dawn begins by writing down the client’s intended use, the evidence already available and the deadline for a reliable answer. That prevents research from becoming an open-ended project and keeps the parties focused on what could change price, terms or willingness to proceed.
Records buyers and sellers should collect
Documents usually reveal more than reassurance. Collect the following records early, preserve the original file names and note the source and date. If a record is missing, label it missing. Do not replace it with an assumption.
- FEMA Flood Insurance Rate Map panel and official map determination used by the lender
- Elevation certificate, survey or other licensed elevation documentation
- Current flood policy declarations, premium information and any transferable rating data
- Prior flood claims, disaster assistance, substantial-damage or repair records available to the owner
- Permits for elevation, flood vents, enclosures, utilities, additions and shoreline work
- Property-specific flood, wind and homeowners insurance quotes with deductibles and exclusions
These records should be read together. A permit without a final inspection, a survey without the referenced easement, or an estimate without a defined scope can create false confidence. Dawn builds one shared checklist and tracks who requested each item, when it arrived and which professional still needs to review it.
Local warning signs that deserve a closer look
- The buyer relies on a seller premium without obtaining a new quote
- An enclosed lower level is marketed as living area without floodplain and permit review
- Mechanical equipment or utilities sit below expected flood elevation
- The map line is treated as a prediction of where water will stop
- A future-risk map, drainage problem or repetitive flooding is ignored because the lender does not require insurance
- The appraisal and insurance files use different building descriptions
A warning sign is not proof of a defect, denial or legal violation. It is a reason to slow down and ask a narrower question. The strongest due diligence says, “Here is what we observed, here is the controlling document or agency, and here is the answer we need before this date.”
In Calvert County, rural land, waterfront, private systems and community restrictions often overlap. One professional cannot answer every layer. A contractor may estimate a repair but cannot guarantee lender acceptance. A county employee may explain permits but not interpret a private contract. A Realtor can organize the transaction but does not replace legal, engineering, insurance or tax advice.
A practical buyer checklist
- Step 1: Search the official FEMA map and County flood tools for the address. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 2: Ask the insurance producer whether an elevation certificate or additional inspection is needed. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 3: Obtain quotes for flood, homeowners and wind coverage before financing deadlines. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 4: Review prior claims and repair permits with appropriate professionals. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 5: Inspect lower-level enclosures, flood vents, utilities, drainage and shoreline exposure. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
- Step 6: Budget premium, deductible, maintenance and mitigation—not only the mortgage payment. Put the result in the transaction file and decide whether it changes affordability, intended use or the offer.
Buyers should prioritize questions that can end the purchase, change the monthly cost or make the planned use impossible. Cosmetic preferences can wait. Title, financing, insurance, safety, legal use and expensive physical conditions cannot. The contract should preserve enough time to receive real answers rather than merely submit requests.
A practical seller checklist
- Seller action 1: Locate elevation certificates, surveys, flood policies and mitigation records. Early documentation protects credibility and gives the seller more choices.
- Seller action 2: Disclose known flooding and claims accurately under applicable requirements. Early documentation protects credibility and gives the seller more choices.
- Seller action 3: Provide permits for elevation, enclosures, utilities and repair work. Early documentation protects credibility and gives the seller more choices.
- Seller action 4: Avoid guaranteeing future premiums or map status. Early documentation protects credibility and gives the seller more choices.
- Seller action 5: Prepare the home so flood vents, equipment and drainage are accessible for inspection. Early documentation protects credibility and gives the seller more choices.
- Seller action 6: Address inconsistent square footage or room-use descriptions before appraisal. Early documentation protects credibility and gives the seller more choices.
Sellers gain leverage by solving uncertainty before a buyer turns it into a worst-case estimate. That does not mean repairing everything or agreeing with every concern. It means describing the property accurately, producing records quickly and understanding the likely cost and timing of any real issue before negotiating.
Related planning: Review Mobile, Manufactured, or Modular? How to Verify the Difference; Review Selling a Home Through a Maryland Estate or Probate; Review Radon Testing and Mitigation Before Home Settlement. These guides are designed to go live together, so the research, financing and negotiation questions connect.
How this issue can affect the transaction
| Area | Possible effect |
|---|---|
| Use | lower levels, storage, utilities and future improvements may be restricted or vulnerable. |
| Financing | the lender may require flood insurance based on its determination. |
| Insurance | premium and deductible depend on policy, building and rating details—not simply the zone name. |
| Appraisal | legal use, elevation, condition and comparable market reaction affect value. |
| Title | easements, shoreline rights and recorded restrictions remain separate from flood mapping. |
| Seller net | premiums, mitigation, repairs or buyer credits can influence proceeds. |
| Resale | complete elevation and permit records reduce uncertainty for future buyers. |
Not every possible effect will apply. The purpose of the table is to prevent tunnel vision. A buyer may solve a physical concern and still have a lender problem. A seller may agree to a credit and still lack insurable title or carrier approval. Each lane must reach its own answer.
Who should answer each part?
| Professional | What that professional should answer |
|---|---|
| Dawn Riley and the real estate team | Organize documents, identify contract deadlines, coordinate questions, compare offer terms and keep advice from each licensed professional in the correct lane. |
| Title company or real estate attorney | Review recorded instruments, ownership, liens, deed language, settlement charges and legal questions. Only an attorney should give legal advice. |
| Lender and appraiser | Decide loan eligibility, underwriting treatment, valuation requirements and documentation. A real estate agent cannot approve financing or direct an appraisal result. |
| Inspector, engineer or specialty contractor | Evaluate physical conditions within the professional scope and explain repair options. A general home inspection does not replace engineering or environmental review. |
| Insurance producer | Confirm whether coverage is available, what it costs, which exclusions apply and what underwriting records are required. |
Dawn’s job is to make sure the correct question reaches the correct professional before the relevant decision date. She can explain the Maryland contract process, organize evidence and negotiate terms. She will not present a guess as a legal, underwriting, engineering, appraisal, insurance or tax conclusion.
A realistic Southern Maryland transaction example
A Broomes Island buyer sees an attractive waterfront price and a seller’s existing flood premium. Dawn asks for the elevation certificate, permit file and claims information, then obtains a new buyer-specific quote. The proposed premium is higher because occupancy and rating assumptions differ. The buyer updates affordability and negotiates with real numbers before the insurance and financing dates expire.
This example is illustrative, not a prediction. Property facts, contract language and professional decisions vary. What remains consistent is the method: identify the uncertainty, obtain the controlling evidence, calculate the effect and decide before leverage disappears.
How Dawn organizes the contract and negotiation strategy
Dawn keeps map status, physical exposure, insurance and intended use in separate lanes. If the buyer needs an elevation certificate or quote, the contract calendar must leave time to obtain it. A general credit does not guarantee insurability or a premium. Any repair agreement should identify the permit, professional, completion evidence and effect on settlement.
Dawn Riley brings more than 25 years of Maryland real estate experience, detailed contract knowledge and Master Certified Negotiator training to that process. Her career includes 1,338+ sales and more than $532,653,786 in volume, with average sold-to-list statistics over 101%. Those numbers do not guarantee a result. They support a disciplined approach to pricing, documentation and negotiation.
Common mistakes to avoid
The first mistake is treating a verbal answer as a permanent fact. The second is asking the wrong professional to guarantee an outcome outside that person’s authority. The third is waiting until settlement week, when moving plans, rate locks and emotions make clear decisions harder.
Another mistake is assuming a credit cures everything. Money can address a known cost, but it does not create a permit, change a title right, make a lender approve the loan or force an insurer to issue coverage. The remedy must match the actual problem.
The Bottom Line
A flood-zone label is a starting point, not a complete risk or insurance answer. Buyers should review the effective map, current and future risk information, building elevation, prior claims, mitigation, lender requirements and an actual insurance quote before deciding that a waterfront or low-lying home is affordable. Collect the records, identify the controlling authority, calculate the transaction impact and protect the deadline. Buyers deserve enough evidence to make an informed decision. Sellers deserve a strategy that does not discount the property simply because information was disorganized.
Frequently Asked Questions
Use FEMA’s Map Service Center and Calvert County’s flood tools. The lender may order its own determination, which controls the lender’s insurance requirement.
No. It generally indicates a different mapped level of risk, not zero risk. Local drainage, future conditions and events beyond mapped scenarios can still affect the property.
It is a standardized record of building and elevation information prepared under applicable requirements. It may support insurance rating, mapping or compliance questions, but it does not itself guarantee a premium or safety.
Do not assume it will transfer on the same terms. The buyer should obtain written guidance and a quote from an insurance professional for the new ownership and occupancy.
No. The lender decides loan and insurance requirements using its flood determination and program rules. Physical risk requires broader mapping, site, engineering and insurance review.
A cash buyer may not have a lender mandate, but should still evaluate potential loss, premium, deductible and personal risk tolerance with an insurance producer.
Permit, building, appraisal and floodplain rules control. The buyer should not rely on décor or listing labels; verify lawful use and valuation treatment.
Claims can inform condition, repairs and insurance. Request available records and have the seller, insurer and appropriate professionals explain the property-specific effect.
Yes. FEMA and communities update maps, and lender or insurance requirements can change. Buyers should consider both current rules and long-term ownership risk.
The insurance quote, map and elevation-document request should begin early enough that the buyer still has contract choices if cost, use or financing changes.
About Dawn Riley
Dawn Riley is an Associate Broker, Realtor, Master Certified Negotiator (MCNE) and Pricing Strategy Advisor (PSA) with The Riley Team at Deep Roots Real Estate in Huntingtown, Maryland. She has more than 25 years of real estate experience and additional negotiation coursework from Yale, Northwestern, UVA, Columbia and UC Davis. Dawn combines strategic pricing, advanced marketing and detailed Maryland contract knowledge for buyers and sellers throughout Calvert County and Southern Maryland.
Career results as of 2026: 1,338+ homes sold, $532,653,786+ in sales volume and average sold-to-list price statistics over 101%, per Bright MLS career production records. Past performance does not guarantee a specific result.
Dawn Riley
Associate Broker, Realtor, MCNE, PSA
The Riley Team at Deep Roots Real Estate
2425 Solomons Island Rd., Suite C, Huntingtown, MD 20639
410-414-2438
dawn@dawnriley.net
Schedule a consultation